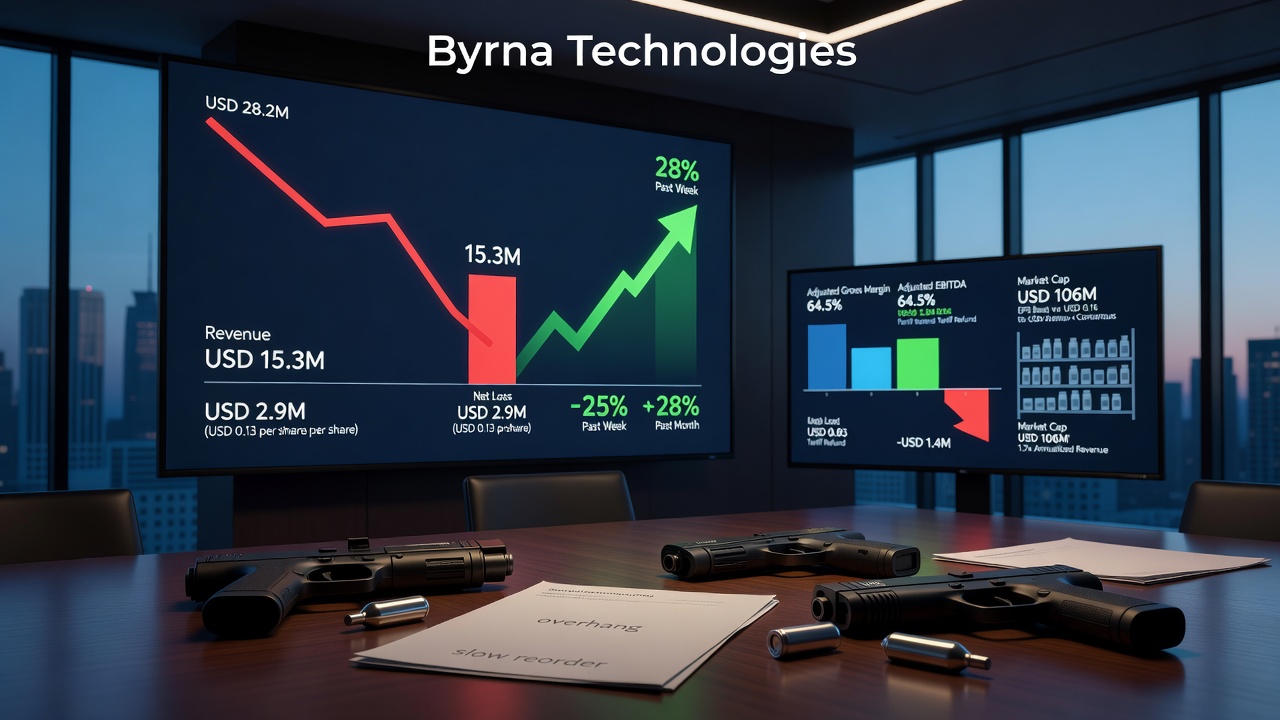
Byrna Technologies posted fiscal third-quarter revenue of USD 15.3 million, down roughly 46% from USD 28.2 million a year earlier, alongside a net loss of USD 2.9 million, or USD 0.13 per share. The maker of less-lethal personal security products said the drop traced back to softer e-commerce demand and slower reorder activity from dealers and chain retailers, a hangover from heavy restocking earlier in the fiscal year that outpaced actual sell-through at the shelf.
The loss per share beat Wall Street's USD 0.16 consensus estimate, a result investors apparently found reassuring enough to send the stock up 25% over the past week and nearly 28% over the past month. That's a notable reaction to a smaller-than-feared loss layered on top of a steep sales decline - the kind of divergence that tends to draw scrutiny once the initial relief rally cools.
Margins Hold Up, But the Mix Matters
Gross profit came in at USD 12.2 million, or 79.5% of revenue, though that figure includes a one-time USD 2.3 million tariff refund that won't repeat next quarter. Strip that out and adjusted gross margin was 64.5%, still up 500 basis points year over year - a genuine improvement, not just an accounting artifact. Adjusted EBITDA, however, swung to negative USD 1.4 million from positive USD 4.1 million a year earlier, which is the number that should give operators and analysts pause. Margin expansion on a shrinking revenue base is a mixed signal at best; it says less about demand strength and more about cost discipline during a slowdown.
Inventory Overhang at the Retail Level
The real story sits in the channel, not the headline numbers. Dealers and chain stores built up inventory during an earlier restocking cycle, then found sell-through running slower than planned. That leaves product sitting on shelves and in back rooms longer than retailers budgeted for, which in turn delays the next round of reorders. It's a familiar pattern in consumer hardware categories: a strong stocking quarter flatters results, then the following quarters absorb the correction. Byrna's management has framed the current period as a transition toward marketing transformation and operational efficiency, language that signals awareness of the problem without yet proving the fix works.
What the Market Reaction Actually Tells You
At a market value near USD 106 million against annualized quarterly revenue of roughly USD 61 million, the stock trades at about 1.7 times sales - not an extreme multiple, but not cheap for a company with declining top-line revenue and negative EBITDA. The EPS beat, a USD 0.03 surprise, or about 20% ahead of consensus, is the kind of result that moves algorithmic and short-term trading flows more than it reflects a change in underlying business health. Note too that the stock actually fell slightly, down 0.11%, in the most recent session - a reminder that much of the rally had already been priced in before the print landed.
For anyone tracking this name, the relevant signals going forward are retail reorder patterns, e-commerce trends, and whether marketing spend translates into actual sell-through rather than just channel stuffing. A one-day stock pop built on a narrower-than-expected loss is not the same as a demonstrated turnaround. The sensible move is to wait for call commentary and the full quarterly filing before drawing conclusions - the headline numbers are a snapshot, not a verdict.
This article is for informational purposes only and does not constitute investment advice. Readers should consult primary filings before making financial decisions.